Ask any experienced truck insurance adjuster what separates fast claims from slow ones, and you will hear the same answer: documentation. Not the severity of the accident, not the size of the claim — the completeness of the file. A claim with every document organized and ready can move from first notice to settlement in weeks. The same claim with documents trickling in one email at a time can take months, with each missing paper generating a follow-up request, a waiting period, and another round of review.
This is the master checklist. It covers every category of document an adjuster is likely to request for a truck insurance claim: scene evidence, vehicle records, driver files, financial documentation, and cargo papers. Work through it once, assemble everything before the investigation gets deep, and you will never be the reason your own claim is waiting. Print it, keep it with your insurance documents, and start filling it the day an incident happens.
Scene evidence: what happened and where
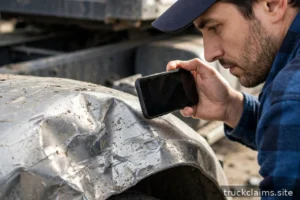
Scene evidence is the most time-sensitive category — it degrades within hours. Your file should include: wide and close-up photos of all vehicles and damage, photos of the road, signage, skid marks, debris, and weather conditions, dashcam footage preserved and backed up the same day, the police report number plus the agency and instructions for obtaining the full report, and names and contact information for all drivers, passengers, and witnesses. If emergency responders were on scene, note the agencies and any incident numbers they provide.
Also include your own written account, made as soon as possible after the incident while memory is fresh: date, time, exact location, direction of travel, weather, traffic conditions, and a factual sequence of events. Do not include opinions about fault — just what you observed. This account becomes your reference for every later retelling, which keeps your statements consistent across the police report, the insurer’s first notice, and any recorded statement. For the full technique on capturing visual evidence, see our guide to documenting truck damage with photos and video.
Vehicle records: the truck’s history
The adjuster will want to know the condition and history of your truck, both to value the damage and to check for policy conditions around maintenance. Assemble: the current registration, the title or lienholder information, maintenance and repair records for at least the past twelve months, the most recent annual inspection report and any recent roadside inspection reports, tire purchase and replacement records if tire failure is involved, and any aftermarket equipment receipts (APUs, liftgates, custom bodies) that add value beyond the base truck.
Maintenance records deserve special attention because they serve two purposes. First, they help establish pre-loss condition — a well-maintained truck with fresh brakes and new tires tells a different story than one with deferred maintenance. Second, some policies contain maintenance-related conditions, and gaps in the records invite questions you do not want. If your records live in a fleet management system, export the relevant vehicle’s history as a PDF; if they are paper, photograph or scan them now, before they fade in a glove box. Organize them chronologically with the most recent first.
Driver file: qualification and hours
For any claim involving a commercial driver, the adjuster will review the driver’s qualification and hours. Have ready: a copy of the driver’s commercial driver’s license (front and back), the current medical examiner’s certificate, the driver’s motor vehicle record if you have a recent pull, hours-of-service logs or ELD data for the day of the incident plus the prior seven days, any post-accident drug and alcohol test results, and the driver’s written statement if one was taken. If the driver was operating under your authority, include the driver qualification file summary.
ELD data is increasingly central to claim investigations — it establishes where the truck was, how fast it was going, and whether hours-of-service rules were followed. Our 2026 guide to electronic logging data explains exactly what adjusters pull from ELDs and how to preserve it. One critical note: know your data retention windows. ELD providers and dashcam systems overwrite or purge old data on their own schedules, so preservation requests should go out in the first days, not the first months.
Insurance papers: your coverage proof
Keep your insurance documents in the same file as the claim, because you will reference them constantly. Include: the declarations page showing coverage types, limits, and deductibles, the full policy (or the relevant coverage sections), any endorsements that modify the base policy, the claim number and adjuster contact information for the current claim, and proof of any other potentially applicable policies — bobtail, non-trucking liability, motor truck cargo, or umbrella — with their claim numbers if you have opened claims under them.
Read your declarations page before your first substantive call with the adjuster. Knowing your deductible, your limits, and which coverages you actually carry prevents two common problems: expecting coverage you did not buy, and failing to claim coverage you did buy. Many truck owners discover mid-claim that they carry valuable coverage they had forgotten about — rental reimbursement, for example, or debris removal — and just as many discover that a coverage they assumed was included was never added. Five minutes with the declarations page at the start saves weeks of confusion later.
Financial proof: establishing what the loss cost
To get paid, you must prove the amount of the loss with documents, not assertions. Your financial file should include: the repair estimate from the shop (and a second independent estimate — adjusters expect this), tow and storage invoices, receipts for emergency mitigation like tarping or load transfers, rental or replacement vehicle costs, and, for downtime claims, the records that prove your lost revenue: settlement sheets, rate confirmations, or dispatch records for comparable periods. For cargo, include the invoice value of the goods, freight bills, and any salvage sale records.
The standard for financial proof is “reasonable and documented.” An adjuster can pay a $4,200 tow bill with an invoice attached; the same adjuster cannot pay a $4,200 tow bill described only in an email. Get invoices for everything, even small expenses — they add up, and undocumented expenses are the first things cut from a settlement. For downtime specifically, be prepared to show not just that the truck was down but what it would have earned: a week of downtime means little without the revenue records to price it, and adjusters will ask for those records before they discuss a number.
Cargo papers: the freight documentation
If cargo is involved, a parallel set of freight documents enters the file: the bill of lading (the single most important cargo document — it is the contract of carriage, the receipt, and the evidence of condition all in one), the freight bill or rate confirmation, the shipper’s invoice showing the value of the goods, delivery receipts with any exceptions noted, temperature logs for reefer loads, weight tickets where weight is at issue, and any correspondence with the shipper or broker about the loss. Photograph the cargo damage as carefully as the truck damage — ideally before anything is moved or salvaged.
Note any exceptions on the delivery receipt at the time of delivery, in writing, before signing. “Subject to inspection” is better than nothing, but specific notes — “three cartons crushed, two pallets wet” — are far stronger. Exceptions noted at delivery are the foundation of every cargo claim; without them, the carrier’s position that the freight arrived intact becomes much harder to overcome. Our cargo claims guide walks through how these documents fit together in the claim itself.
How to organize and deliver the file
Having the documents is half the job; delivering them in a way the adjuster can actually use is the other half. Create one digital folder per claim with subfolders matching the categories above. Name files descriptively: “police-report-2026-07-02.pdf” beats “scan003.pdf” by a mile. Convert everything to PDF where possible, keep photos as JPEGs with dates in the filenames, and maintain a simple cover log listing each document, the date sent, and the method.
Send documents in complete batches rather than one-off emails, and confirm receipt of each batch in writing. After sending, keep your originals — never give away your only copy of anything. And set a calendar reminder to follow up if you have not received acknowledgment within a few business days; adjusters handle enormous caseloads, and a polite confirmation request is normal professional practice, not pestering. For the step-by-step claim process this documentation feeds into, follow a structured filing sequence from first notice through settlement.
Frequently asked questions
What if I am missing some documents on this checklist?
Submit what you have and note what is pending with expected dates. Adjusters work with incomplete files routinely — what stalls claims is not missing documents but silence about them. A note saying “ELD export requested from provider, expected Friday” keeps the file moving; saying nothing invites a follow-up letter in two weeks.
How long should I keep claim documents after the claim closes?
At least one year for straightforward property claims, and longer — matching your state’s statute of limitations — if injuries were involved or the claim was disputed. Digital storage is cheap; the cost of needing a document you deleted is not.
Do I need originals, or are copies enough?
Copies are fine for the adjuster’s file in nearly all cases. Keep your originals (or the authoritative digital versions) in your own records. The exceptions are rare — typically only sworn proof-of-loss forms, where the insurer may require an original signature.
Should I send everything at once or wait to be asked?
Send the core file proactively — scene evidence, vehicle records, driver file, and insurance papers — and hold specialized documents until relevant. Proactive completeness signals credibility and shortens the investigation; dribbling documents out over weeks signals the opposite.
Documentation is the one part of the claim process entirely within your control. You cannot control the adjuster’s caseload, the repair shop’s schedule, or the other party’s cooperation — but you can control whether your file is complete, organized, and delivered. Build it once, build it early, and the rest of the claim gets measurably easier.