The insurance adjuster is the single most important person in your truck claim — more important than the agent who sold you the policy, more important than any customer-service representative. The adjuster investigates the loss, decides what the policy covers, sets the reserve (the amount the insurer expects to pay), negotiates the settlement, and recommends whether the claim gets paid, reduced, or denied. Yet most claimants walk into the process with only a vague idea of what the adjuster actually does, which leads to mismatched expectations, frustration, and avoidable conflict.
This guide explains the adjuster’s real job from the inside: what they are responsible for, what constrains them, what they cannot do no matter how much you ask, and how the relationship differs depending on whether they work for your insurer or the other party’s. Understanding their role will not just reduce your stress — it will make you a more effective claimant, because you will know exactly what to give them, what to ask for, and where the real decisions get made.
The adjuster’s actual job
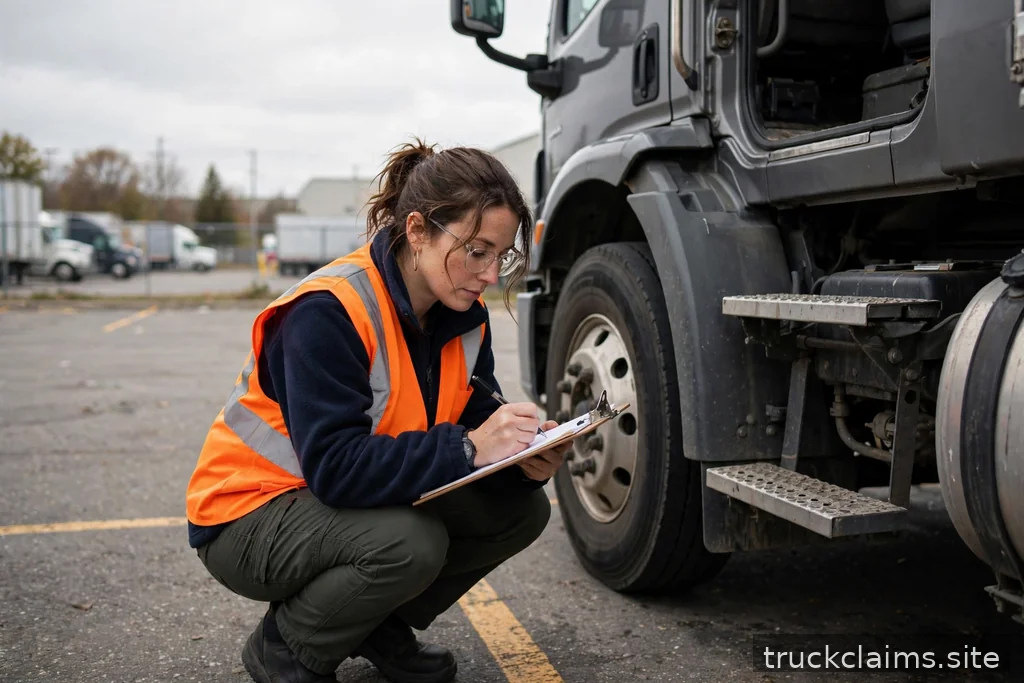
An adjuster’s job has four parts: investigate, evaluate coverage, value the loss, and resolve the claim. Investigation means gathering the facts — reviewing your documents, inspecting the damaged truck, taking statements, contacting witnesses and the other parties, and pulling records like police reports and ELD data. Coverage evaluation means reading your policy and deciding which parts of the loss fall within the coverage you purchased and which do not. Valuation means putting a dollar figure on the covered loss: repair costs, actual cash value, downtime, cargo value. Resolution means negotiating a settlement with you and getting the claim closed and paid.
Notice what is not on the list: the adjuster is not your advocate, not your advisor, and not a neutral judge. Even your own insurer’s adjuster works for the insurance company, not for you — their professional obligation is to handle your claim fairly under the policy and the law, which is a real obligation, but it is not the same as being on your side. Adjusters who are courteous and helpful are doing their jobs well; adjusters who seem to be looking for reasons to reduce the payment are also, in a sense, doing their jobs. Keeping this framing in mind prevents the most common emotional mistake in claims: treating the adjuster as either a friend or an enemy, when they are neither.
What constrains the adjuster
Adjusters operate inside constraints that claimants rarely see. The most important is authority: most adjusters can only settle claims up to a certain dollar limit on their own authority, and anything above that must be approved by a supervisor or manager. This is why negotiations sometimes stall at a particular number — the adjuster may literally be unable to go higher without approval, and getting that approval takes time and justification. When an adjuster says “I’ll need to run that by my supervisor,” they are usually telling the truth.
The second constraint is the reserve. Early in the claim, the adjuster sets a reserve — an internal estimate of what the claim will cost — and reserves are watched closely by management. An adjuster who sets reserves too high gets questioned; one who sets them too low and then needs increases also gets questioned. This creates a structural conservatism: adjusters are professionally cautious about recognizing the full value of a claim early. Understanding this helps you interpret behavior that otherwise feels personal — the low initial offer, the reluctance to acknowledge newly discovered damage — as systemic rather than adversarial.
Your adjuster vs. their adjuster
The adjuster’s obligations to you depend entirely on whose insurer employs them, and this is the distinction that matters most in practice. Your own insurer’s adjuster owes you the duties in your policy and your state’s insurance laws — typically including good faith, fair dealing, timely communication, and a reasonable investigation. If your insurer handles your claim in bad faith — unreasonably denying a covered claim, for example — you may have legal remedies beyond the policy itself. This contractual relationship is your leverage: you paid for coverage, and the insurer must deliver what the contract promises.
The other party’s adjuster owes you essentially nothing. Their duty runs to their policyholder, and their job is to resolve your claim against their insured for as little as possible while staying within the law. They will be professional and often friendly, but every question they ask and every statement they take serves their employer’s interest. This is why the communication rules differ so sharply: cooperate fully and proactively with your own adjuster, and be polite, factual, and minimal with the adverse adjuster. Never give the adverse adjuster a recorded statement without understanding the implications — our guide to recorded statements explains the ground rules.
What the adjuster can’t (or won’t) do
Adjusters cannot give you legal advice, and you should not treat their explanations of your rights as authoritative — they explain the insurer’s position, which is not the same thing. They cannot waive policy provisions informally; if an adjuster tells you something is covered, get it in writing, because the written policy controls over oral assurances. They cannot pay for things outside the policy no matter how sympathetic your situation is — an adjuster who wants to help you still cannot manufacture coverage that does not exist.
Adjusters also will not do your documentation work for you. They will request documents, but assembling your file is your job — and as our documentation checklist shows, the claimants who build complete files get faster, better outcomes. Finally, adjusters will not volunteer the maximum the insurer might pay; negotiation is an expected part of the process, and the first offer is virtually never the last word. Understanding these limits prevents the disappointment of expecting the adjuster to be something they are not, and focuses your energy where it actually moves the claim.
How to work well with your adjuster
The most effective claimant posture is organized, responsive, and businesslike. Respond to requests within a day or two. Send documents in labeled batches with a cover note. Keep a log of every interaction — date, who you spoke with, what was discussed, what was promised. Confirm important conversations in a follow-up email. Ask what the adjuster needs next rather than waiting to be asked. This is not about being liked; it is about making your file the easiest one on the adjuster’s desk to move forward, because easy files get attention and difficult files get deferred.
At the same time, protect your interests in writing. Get coverage decisions explained in writing. Get settlement offers broken down in writing. If the adjuster makes a verbal promise — “we’ll cover the rental” — confirm it by email the same day. And know the escalation path: if your adjuster is unresponsive or unreasonable, you can ask for a supervisor, file a complaint with your state’s insurance department, or consult a professional. These are normal parts of the system, not nuclear options, and an adjuster who knows you understand the process treats your file with corresponding care. For the inspection phase specifically, read our guide to preparing for the adjuster’s inspection.
Red flags: when the adjuster relationship goes wrong
Most adjuster relationships are professional and productive. But watch for patterns that signal real problems: repeated requests for documents you already provided (suggesting the file is disorganized or the claim is being slow-walked), long unexplained silences after promised deadlines, pressure to accept a settlement before the full loss is known, misstatements about what your policy covers, or hostility when you ask questions. Any one of these occasionally is normal friction; a pattern is a problem.
When you see a pattern, escalate methodically: first a written request to the adjuster restating the issue and asking for resolution by a specific date, then a request to speak with a supervisor, then a complaint to the state insurance department if the conduct violates claim-handling regulations. Document everything — regulators and supervisors respond to paper trails, not to frustration. And if the claim involves significant money, disputed liability, or injuries, this is the point where professional guidance starts paying for itself.
Frequently asked questions
Can I request a different adjuster?
You can ask, and insurers sometimes reassign files for workload or conflict reasons, but there is no right to choose your adjuster. A more effective approach is usually to escalate specific issues to a supervisor in writing — that creates accountability without depending on reassignment.
How many claims does an adjuster handle at once?
Often dozens to over a hundred, depending on the line and complexity. This is why organized, responsive claimants get better service: your file competes for attention with all the others, and the easy, complete files move first.
Does the adjuster decide my claim alone?
For routine claims within their authority, largely yes. For large or complex claims, supervisors, managers, and sometimes coverage counsel are involved. If your claim is significant, assume multiple people are reviewing the file and document accordingly.
Should I be friendly with the adjuster?
Professional and courteous, always — it costs nothing and helps. But keep the relationship businesslike: confirm things in writing, know your policy, and remember that even the friendliest adjuster works for the insurance company, not for you.
The adjuster is the person who will decide more about your claim’s outcome than anyone else, so understanding their job is practical, not academic. They investigate, evaluate coverage, value the loss, and negotiate settlement — inside constraints of authority, reserves, and policy language, owing contractual duties to their own policyholders and essentially none to adverse claimants. Work with your own adjuster as an organized partner, treat the adverse adjuster with polite caution, put everything important in writing, and you will navigate the relationship the way the system is designed to be navigated.